
When can you enroll, do you qualify after a life change, and where should you apply? Providence health insurance rules depend on where your healthcare coverage comes from, along with your state, county, and plan type.
A missed date can delay care and create an expensive coverage gap. Plan availability, costs, and deadlines also change by plan year, so confirm current details with Providence, another health insurer, your state Marketplace, your employer, or Medicare before submitting an application.
Start by identifying the coverage path that fits your situation.
Key Takeaways
- Providence plans and provider networks vary by state, county, coverage type, and plan year.
- Individual and family coverage typically has an annual open enrollment period. Employer and Medicare coverage follow separate calendars.
- A qualifying life event may open a Special Enrollment Period outside the annual enrollment window.
- Compare doctors, prescriptions, deductibles, and out-of-pocket maximums before choosing a plan.
- Coverage doesn’t begin until you complete all required steps, including the first premium payment when applicable.
Providence Health Insurance Enrollment Guide: Start With the Right Coverage Path
Your enrollment route determines which health insurance plans, forms, deadlines, and financial assistance apply. A person shopping for an individual or family plan may use a state Marketplace or an insurer’s direct enrollment process. Someone offered employer-sponsored commercial coverage follows the employer’s benefits calendar instead, including elections for employer group plans.
Eligible adults may find Providence Medicare Advantage or Medicare Supplement options, along with supplemental plans. Medicare enrollment calendars differ from Marketplace rules. Medicaid plans and CHIP may allow year-round enrollment for eligible residents based on income and location. The Providence Health Plan coverage overview lists individual, employer, Medicare, and Oregon Health Plan options.
Check Whether Providence Plans Are Available Where You Live
A recognizable insurer name doesn’t mean every plan is available in every county. Providence operates a health system, and its clinics and facilities may not participate in every insurance product. Covered health services, benefits, and provider access can vary by plan and location.
Use Providence’s plan search tools and the relevant Marketplace to check your address. Oregon residents can review options through the Oregon Health Insurance Marketplace, which offers plan and savings comparisons. Before enrolling, check whether your local Providence Medical Group clinic participates in the exact plan. Also confirm coverage for your preferred hospital, specialists, pharmacy, and current prescriptions.
Know Which Enrollment Rules Apply to Your Situation
Marketplace enrollment follows annual open enrollment and Special Enrollment Period rules. Employer coverage often has its own annual benefits election window, while Medicare has several enrollment periods tied to age, eligibility, and plan changes.
Therefore, don’t use a general deadline until you know whether your coverage comes through an employer, Medicare, a Marketplace, or a state program. Medicaid and CHIP enrollment may remain open year-round for people who qualify.
Open Enrollment Deadlines for Providence Plans
Open enrollment is the scheduled yearly period for joining or changing most individual and family health plans without a qualifying life event. Exact dates vary by state and plan year, so a past deadline isn’t a reliable guide for the next application cycle.
For example, Providence states that its 2026 individual and family open enrollment ended January 15, 2026, on its qualifying events page. That date doesn’t automatically apply to every state, employer, or future plan year. Confirm current dates with the applicable Marketplace, employer, insurer, or official Providence source.
How the Application Deadline Affects Your Coverage Start Date
The application deadline and coverage effective date are different. Many enrollment systems use monthly cutoffs. An application submitted early enough may start on the first day of the following month.
For instance, a plan may show a February 1 effective date when you finish enrollment by its January cutoff. A later completed application could start March 1 instead. Review the effective date displayed in your enrollment confirmation before you pay the first premium.
A submitted application does not always mean your coverage has started. Check for an approved plan selection, an effective date, and any required payment.
What to Do if You Miss Open Enrollment
First, check whether a recent life event gives you a Special Enrollment Period. You may also qualify for Medicaid or CHIP, gain access to employer coverage, or continue a former employer plan through COBRA.
Short-term health plans may be legal in some places, but they aren’t direct replacements for ACA-compliant coverage. They can exclude preexisting conditions, routine care, prescription benefits, or other essential services. Read the policy limits before relying on one.
Special Enrollment After a Life Change
A Special Enrollment Period, often called an SEP, may let you enroll outside open enrollment after a qualifying event. The event date, required proof, and coverage start rules matter as much as the event itself.
Report the change as soon as possible. Keep copies of notices, uploaded documents, emails, and confirmation numbers in one folder. Missing documents can delay a coverage decision.
Qualifying Life Events That May Open a Special Enrollment Period
Common qualifying events include losing qualifying job-based coverage, getting married, having or adopting a child, moving permanently to a new service area, leaving incarceration, or losing Medicaid eligibility.
However, voluntarily dropping coverage or failing to pay premiums usually doesn’t create an SEP. Some moves also require proof of prior coverage or a previous residence. Review the requirements for your specific event before canceling a current plan.
Documents and Deadlines for a Special Enrollment Application
Useful documents may include a coverage termination letter, former insurer notice, marriage certificate, birth or adoption record, lease, utility bill, or proof of a new address. Choose documents that clearly show names and dates.
Marketplace applicants often have a limited enrollment window around the event. The window length depends on the event and current rules. Submit requested proof quickly, since the Marketplace or insurer may wait for verification before finalizing coverage.
Compare Providence Plans Before You Enroll
A low monthly premium can look attractive until you need specialist care, expensive prescriptions, or a hospital visit. Compare the full cost structure: premiums, deductible, copays, coinsurance, and the annual out-of-pocket maximum. These costs shape access to expected patient care.
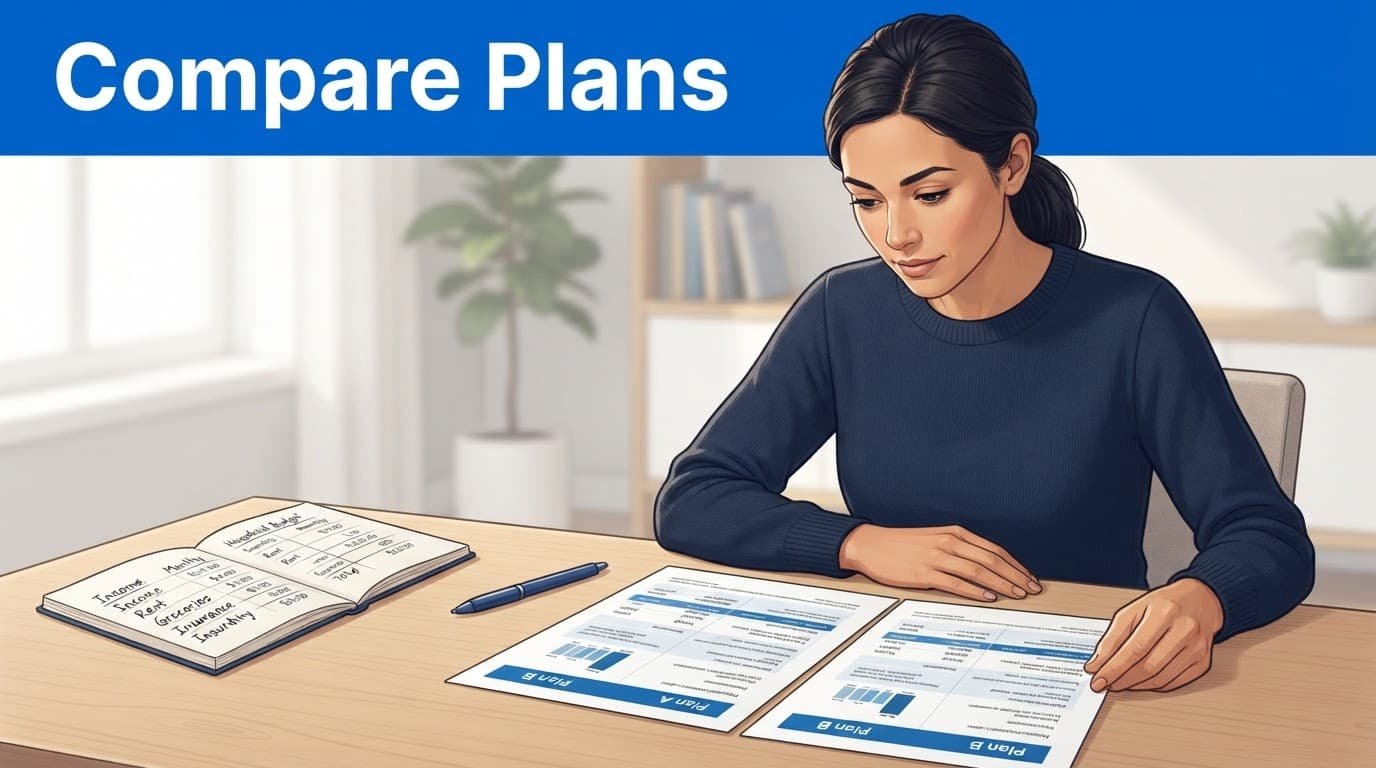
Marketplace financial help can lower monthly costs for eligible households. Yet employer plans and Medicare use different cost systems. Use the Providence individual and family plan information to review the options sold in your area.
Verify Doctors, Hospitals, Prescriptions, and Referral Rules
Check the provider directory using the exact plan name, not only the insurer’s name. The plan’s insurance network determines access. Confirm your primary care doctor, regular specialists, preferred hospital, nearby urgent care, pharmacy, and each ongoing medication. If you use Providence Medical Group, confirm it participates in the exact plan.
HMO-style plans often require you to stay in-network and may require referrals for specialty care. PPO-style plans can offer broader access, though out of network care can cost much more. Recheck the provider directory for referral and network rules. Call customer service and the provider’s office when information is unclear, since the provider directory can change.
Estimate Premium Assistance and Total Annual Costs
Estimate costs using this simple formula:
Annual premiums + expected medical spending = likely yearly cost
Then compare that number with each plan’s out-of-pocket maximum for a high-cost year. Marketplace assistance depends on household income, household size, location, and eligibility rules. Report income changes promptly because they can affect your tax credit and repayment amount.
How to Apply for Providence Health Insurance and Confirm Enrollment
Gather Social Security numbers or immigration documents where applicable, household income information, current coverage details, and dates for any qualifying life event. Then compare available plans through the correct enrollment channel.
After you choose a plan, review the eligibility result and submit the enrollment application. Pay the first premium if required. Save the confirmation page, payment receipt, policy documents, and insurance card once it arrives. New health plan members should also save the member ID number from the card or member portal.
Providence has announced that it will not offer individual and family plans in 2027 or beyond. This affects Providence’s insurance business, not every service offered through its health system. If you need individual coverage for 2027, use your state Marketplace and compare current insurers rather than assuming a Providence plan will be available.
Where to Get Help With Enrollment Questions
Providence Health Plan customer service can answer plan and network questions through official enrollment resources. A state Marketplace can explain eligibility, financial assistance, and SEP documentation. Certified enrollment assisters and licensed agents may also help with applications.
For workplace coverage, contact your employer’s benefits administrator. Medicare questions belong with Medicare or a licensed Medicare adviser, including questions about Medicare Advantage enrollment. Medicaid questions belong with your state Medicaid office. Ask customer service for written confirmation when a deadline or eligibility decision isn’t clear.
Frequently Asked Questions
Can I keep my Providence doctor if I change plans?
Maybe, but you must check the new plan’s provider directory. A doctor can participate in one Providence network and not another. Call the doctor’s office and customer service to confirm participation in the exact plan before you enroll.
Does paying my first premium activate coverage immediately?
Usually, no. Your coverage starts on the effective date listed in your enrollment confirmation, provided you completed required payment and documentation steps. Keep the payment receipt until your member portal or ID card confirms active coverage.
Can I change plans after I enroll?
You can usually change plans during open enrollment. Outside that period, you generally need a qualifying event or another enrollment opportunity. Medicare Advantage, employer coverage, Medicaid, and Marketplace plans follow different change rules.
What happens if my income changes after I receive Marketplace savings?
Update your Marketplace application as soon as your income or household changes. Your premium tax credit may increase or decrease, and waiting can create a repayment issue when you file taxes.
Is COBRA cheaper than a new Marketplace plan?
It depends on your former employer contribution, income, and available subsidies. COBRA often lets you keep the same provider network, while a Marketplace plan may cost less with financial assistance. Compare premiums and benefits before deciding.
Make the Enrollment Decision With Current Details
The best enrollment plan starts with the right coverage route, not a guessed deadline. Check your current open enrollment or Special Enrollment rules, compare total costs and networks, then apply through an official channel.
After payment, confirm your effective date and that covered health services will be accessible once coverage begins. Keep every enrollment record. Plan availability and deadlines can change, so verify the details for your state and plan year before making a final choice.
Individual Health Insurance Plans in the USA: A 2026 Guide to Coverage and Costs